

Simple Checkbook Ledger
3.4

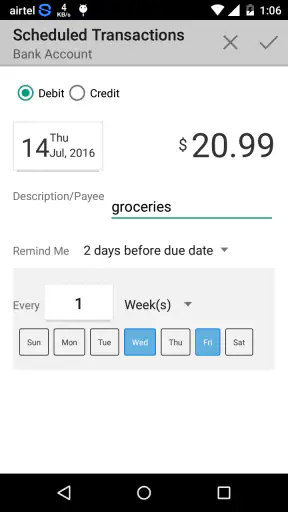
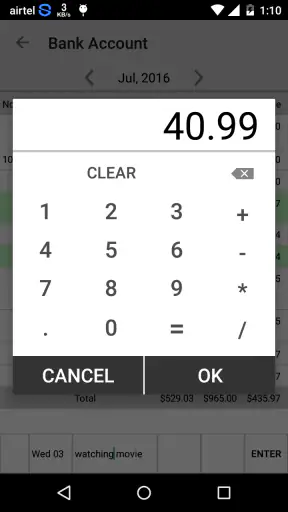
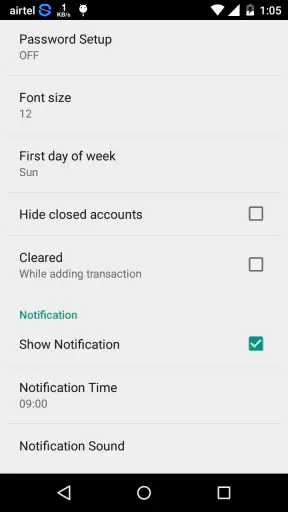
I started using Simple Checkbook Ledger with a very ordinary problem in mind: keeping track of money that moves through more than one account without turning a household budget into a full-time project. The app sits in the finance category and takes a deliberately narrow approach. Instead of trying to be a complete banking service, it focuses on recording account activity in a checkbook-style ledger. That simplicity is its main appeal, but it also defines where the app stops being the right tool.
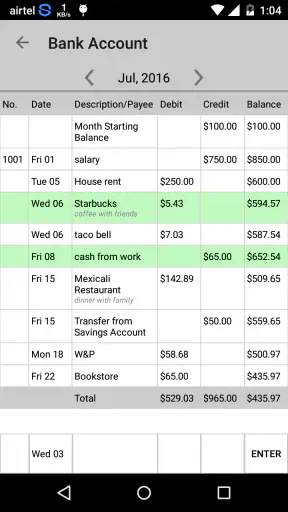
In my experience, this is most useful when I want a clear running record of spending, deposits, transfers, and the balance I expect to have. I can open the ledger, enter a transaction, and continue with my day. There is no need to learn a large financial dashboard before making a simple entry. For someone who still thinks about money in terms of account registers, this feels familiar and practical.
The app is free to install, with optional in-app purchases priced at $1.99 per item. It is made by Teelu Apps, has an Everyone content rating, and requires iOS eleven or later. Its current version is 3.5. The app has been available since August 3, 2016, and its long presence helps explain why the design feels more like a traditional checkbook tool than a modern financial command center.
How Simple Checkbook Ledger works in a shared household
A useful ledger for one person or a shared device
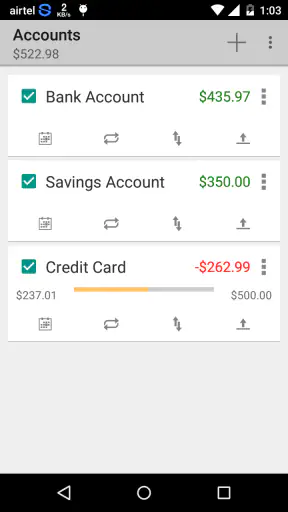
The most convincing use case is a household where people need to see the same account picture from the same device. Imagine a couple using one tablet or phone to track a checking account used for groceries, utilities, and small daily purchases. One person pays the electricity bill, while the other buys supplies on the way home. If both entries are recorded in the same ledger, the expected balance is easier to follow than it would be from memory.
That workflow requires an agreement: every person who uses the account must enter transactions consistently. The app can serve as a common record, but it does not replace communication. If one person forgets to record a card payment, the ledger may look healthier than the bank account. I would therefore treat it as a shared bookkeeping surface, not as an automatic source of truth.
This distinction matters because a manually maintained checkbook has a different rhythm from an app that connects directly to financial institutions. With Simple Checkbook Ledger, the value comes from deliberate entry. That can be a strength for people who want to notice where money is going, but it is extra work for anyone who expects automatic synchronization.
Keeping account boundaries clear
One of the first habits I recommend is deciding what each account represents before entering transactions. A household might keep a personal checking account, a shared spending account, and a savings account. Mixing all three into one running stream makes the ledger harder to trust, even if every individual entry is correct.
I would create a separate record for each account and use a consistent naming style that everyone in the household understands. For example, “shared bills” is more useful than an inside nickname that only one person recognizes. This is a small organizational choice, but it prevents the common mistake of recording a transfer as income or treating a purchase from one account as if it came from another.
Transfers deserve particular attention. When money moves between two accounts, it should be represented as a movement between those accounts rather than as new household income. That distinction helps preserve a realistic view of available money. If the app makes you enter both sides manually, the process takes longer, but it also gives you a chance to check that the sending and receiving balances agree.
The most important discipline is to separate account ownership from account purpose. A personal account can still pay a shared expense, and a shared account can still contain money contributed by only one person. Recording the account used, rather than guessing who “owns” the expense, keeps the ledger grounded in what actually happened.
A realistic weekly routine
My preferred routine would be a short entry session after shopping or bill payment, followed by a weekly review. During the week, I would record the date, amount, account, and a plain-language note while the receipt or notification is still available. At the weekly review, I would compare the ledger with the bank balance and look for pending card payments, forgotten cash spending, or duplicated entries.
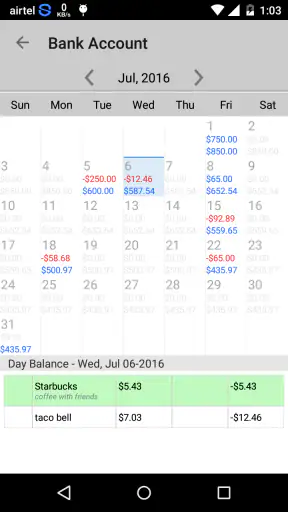
This approach is especially helpful when a household has several small purchases that are easy to overlook. A coffee, a parking fee, and a pharmacy visit may not look important individually, but together they can explain why the expected balance feels wrong. A checkbook ledger encourages those small transactions to be visible instead of leaving them buried in a bank statement.
For shared use, I would also choose one person to perform the weekly reconciliation, even if everyone is allowed to enter transactions. That is not a limitation of the app so much as a practical rule. When responsibility is vague, two people may assume the other has checked the balance. A simple division of duties makes the record more dependable.
What setup should look like
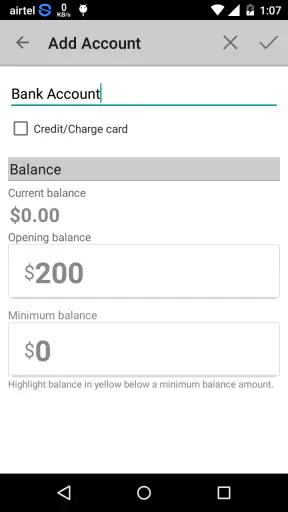
Setup is best approached as a boundary-setting exercise rather than a race to enter old financial history. I would begin with the current balance of each account and add only the transactions needed to make that starting point understandable. Recreating months of past purchases can take time without improving daily usefulness.
Before handing the device to another household member, I would agree on a few conventions. Decide whether entries use merchant names or broad descriptions, whether pending card payments are recorded immediately, and how reimbursements are labeled. A shared ledger becomes confusing when one person writes “market,” another writes “groceries,” and a third records only the card name.
I would also keep household and personal records separate in my own thinking. If a roommate uses the same device, that does not mean every account should be visible in the same working routine. The app can be useful for a shared account while personal finances remain outside that ledger. That boundary is important because convenience should not automatically become financial exposure.
The free price makes experimentation easy, and the Everyone rating means the app is presented as suitable for a broad audience. Still, suitability is not the same as financial readiness. A younger user may understand how to enter a transaction but not understand why a pending payment changes what is safely spendable. An adult should explain the difference between the ledger balance, the bank’s available balance, and money that has already been promised to a bill.
Coordinating without creating confusion
Coordination works best when the app is treated as a shared notebook with agreed rules. I would avoid using vague notes such as “paid back” without identifying the reason. A clearer entry might say that a household member reimbursed the shared account for a particular purchase. That makes later checking much easier, especially when several reimbursements happen close together.
For recurring bills, I would create the entry when the payment is actually scheduled or made, not simply because the bill normally arrives around the same time. Predictable habits are useful for planning, but assuming that a payment has happened can produce a misleading balance. The ledger should reflect completed or intentionally recorded activity, not an idealized calendar.
Another useful practice is to mark unusual transactions with notes that explain their context. A large grocery trip, an annual renewal, or a cash withdrawal can otherwise look like an unexplained error during reconciliation. These notes are not decorative; they reduce the time needed to investigate a balance that does not match expectations.
There is also a trade-off between detail and speed. If every entry includes extensive commentary, daily recording becomes burdensome and people may stop doing it. If entries contain almost no context, the weekly review becomes guesswork. I would use detailed notes for exceptions and short, consistent labels for routine purchases.
Age, trust, and financial responsibility
The Everyone age rating makes the app approachable for a household that wants to teach basic money tracking. I can imagine a parent using a shared device with a teenager to record allowance deposits, transport costs, or spending from a designated account. The useful lesson is not simply how to type an amount; it is how each transaction affects the remaining balance.
That kind of teaching needs supervision. A ledger entry is not proof that money exists, and a child who can edit a record may not understand the consequences of changing it. I would use the app as a conversation aid, checking entries together at first and explaining why accuracy matters. It should not be treated as a substitute for an adult’s oversight of a young person’s finances.
Trust is equally important among adults. If several people share a device, everyone should know which accounts are being recorded and who is responsible for corrections. I would not assume that a shared ledger provides privacy separation or individual permissions. The safest approach is to include only accounts that the users have explicitly agreed to manage together.
For a roommate arrangement, this means limiting the ledger to rent, utilities, and agreed shared purchases. Personal income and unrelated spending do not need to enter the same record. For a family, it may mean keeping a household account visible while maintaining separate personal accounts elsewhere. The app’s value increases when the boundaries are simple enough that everyone can follow them.
Where it compares well with other finance tools
Compared with a bank application, Simple Checkbook Ledger is less convenient for checking live account information but more focused on intentional record keeping. A bank app shows what the institution knows; a checkbook ledger shows what you have chosen to record and anticipate. If you regularly need current transaction status, card controls, transfers initiated through the bank, or account alerts, the bank’s own app is the better primary tool.
Compared with a full budgeting application, this ledger is likely to feel lighter and less demanding. Budgeting tools often organize spending into categories, goals, reports, and long-term plans. Those features can be valuable when I want to analyze household patterns, but they can also create setup work that is unnecessary for someone who mainly wants an accurate running balance.
Compared with a spreadsheet, the app is more convenient for quick entries on a phone, while a spreadsheet offers greater flexibility for custom formulas and shared collaboration. A spreadsheet may be preferable for a household that needs detailed cost splitting, tax records, or a tailored monthly model. Simple Checkbook Ledger makes more sense when the desired workflow is close to a traditional register.
The choice therefore depends on the question I need answered. If the question is “What should the balance be after the transactions I have recorded?” this app is a sensible fit. If the question is “How much did each person spend by category across the year?” I would look toward a budgeting or spreadsheet solution instead.
Practical limitations to consider
The manual nature of the ledger is the biggest source of friction. It rewards users who enter transactions promptly and review them regularly. It is less forgiving when a household makes many purchases across different cards, uses cash frequently, or expects every account to update automatically.
The app’s average rating is 3.4 from around two and a half thousand ratings, with roughly one and a quarter thousand written reviews. I read that overall signal as a reason to keep expectations measured. The concept is useful, but a checkbook tool can feel limited if your financial life has moved beyond straightforward account registers.
The current version, 3.5, is worth checking against your device before committing to a household workflow. Since the minimum operating system is iOS eleven or later, older devices may not be suitable. I would also test the exact entry and review process with a small, noncritical account first, rather than migrating every household record immediately.
In-app purchases cost $1.99 per item, so I would consider them only after deciding that the basic workflow fits. The free starting point is useful because it lets me judge whether manual recording is realistic for my habits. Paying for an option does not solve the central question of whether everyone will consistently maintain the ledger.
Who should use it and who should skip it
I would recommend Simple Checkbook Ledger to someone who likes the clarity of a checkbook register, wants to track one or several accounts manually, and prefers a focused finance app over a large budgeting system. It is particularly suitable for a household that can agree on account boundaries and assign responsibility for regular reconciliation.
It can also work well for a person who wants to separate a specific purpose, such as household bills or a small spending account, from a more complicated overall financial picture. Keeping the scope narrow makes the app easier to maintain and reduces the temptation to turn every financial decision into a data-entry task.
I would skip it as a primary solution if automatic bank synchronization is essential, if several people need separate access rules, or if detailed category reporting is the main goal. In those cases, a bank app, budgeting service, or carefully designed spreadsheet may save more time. I would also avoid relying on it alone for business bookkeeping, tax preparation, or any situation where formal records and audit trails are required.
My household verdict
After looking at the app through a shared-household lens, I see a straightforward tool with a clear purpose. It does not need to be the center of every financial task. Its best role is smaller: a common ledger for accounts that people intentionally manage and review together.
The app’s free entry point, familiar checkbook style, and broad age rating make it easy to try with a partner, roommate, or older child. The important condition is that users understand the limits of a manually maintained record. The ledger is only as current as the last entry, and a shared device does not automatically create privacy, permissions, or accountability.
My final recommendation is cautious but positive. If you want a simple way to record account activity and you are willing to build a consistent household routine, Simple Checkbook Ledger is worth trying before moving to a heavier budgeting tool. Start with one clearly defined account, agree on naming and reconciliation rules, and see whether the habit survives a normal week. If it does, the app can provide a clean, understandable view of shared money. If it does not, the problem is probably not a missing feature; it is a sign that an automatic or more collaborative alternative would suit your household better.
3.4
1.24K Reviews
Pros
- Simple layout makes daily income and expense entries quick to record.
- Supports separate accounts for tracking cash
- bank
- and other balances.
- Running balances help users monitor spending without complex budgeting tools.
- Useful for people who prefer manual control over automated bank connections.
- Lightweight design should work well on older or less powerful devices.
Cons
- Manual entry can become tedious for users with many daily transactions.
- Limited automation may require more effort than full-featured finance apps.
- Basic reporting may not satisfy users seeking detailed spending analysis.
- Users must regularly back up data to avoid losing their financial records.
- The straightforward interface may feel too minimal for advanced budget planning.


